When a storm damages your roof, the insurance process can feel confusing. Family Tree Roofing helps by documenting the damage clearly, explaining what we found, and making the repair or replacement straightforward once your claim is decided. Your insurance company decides coverage; our job is to give you accurate, well-documented information about your roof that you can share with your insurer.
How we help with a roof claim
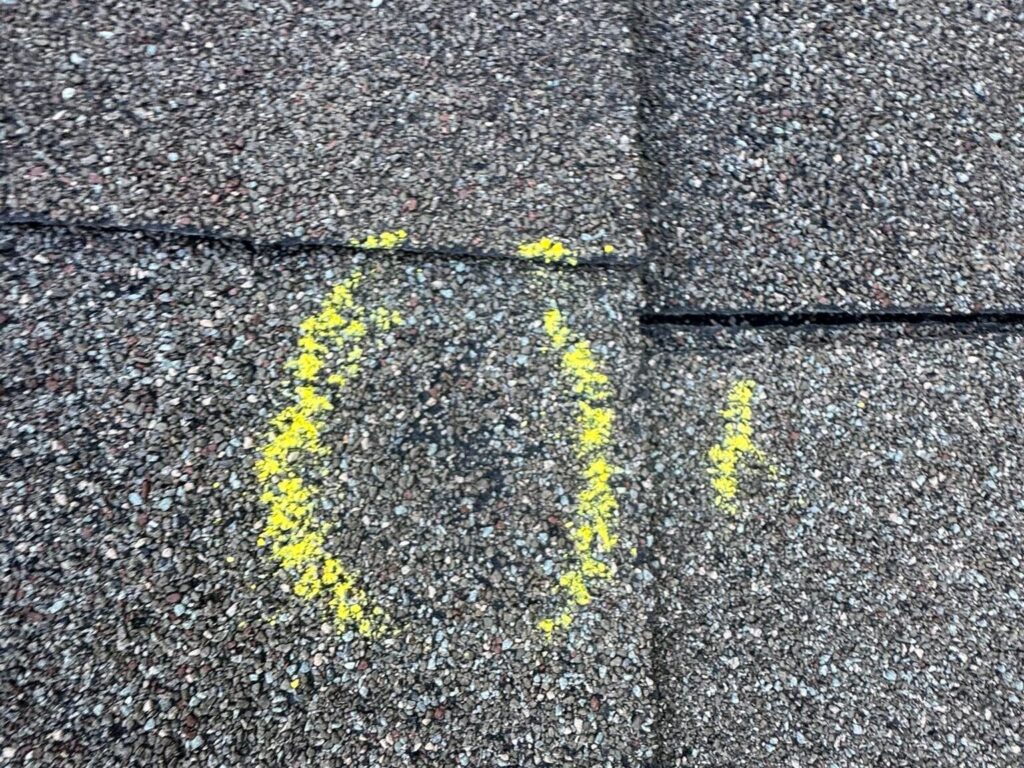
- Free inspection and photos. We document hail and wind damage on the roof, flashing, vents and gutters.
- A clear explanation. We tell you whether the damage looks storm-related and what it would take to repair or replace.
- Repair first when it will do. If the damage is limited and the roof can reasonably be repaired, that is what we recommend, even when a replacement claim might be possible.
- A documentation package. Photos and a written estimate covering the work that is actually needed, in a form you can hand to your insurance company yourself. The aim is that you have it before the adjuster arrives, so the adjuster can verify what we found.
- The work itself. Once you decide to move forward, we handle the repair or replacement and cleanup.
The usual steps
- Schedule a free inspection so you know what condition the roof is in and whether there is storm damage.
- If there is, contact your insurance company to report the claim. You are the policyholder, so the claim is yours.
- Your insurer sends an adjuster to inspect the roof. Having our documentation package before that visit lets the adjuster check each item we recorded against the roof itself.
- Review your insurer’s decision and estimate. Ask your insurer about anything you do not understand.
- Approve the work and schedule your repair or new roof.
What we do not do
We do not pay or waive deductibles. Oklahoma law prohibits roofing contractors from advertising or promising to pay any part of a homeowner’s insurance deductible, and an insurer is not required to consider an estimate from a contractor who does. Your deductible is your responsibility under your policy.
We are roofers, not insurance adjusters or attorneys. We do not file your claim, negotiate it on your behalf, interpret your policy or predict what your insurer will decide. For questions about coverage, deductibles or claim decisions, talk with your insurance agent or company.
Filing a claim? Get the roof documented first.
Tell us what is going on and we will set a time that works for you. No pressure, no obligation — just clear answers from a local, family-owned team.
Related: storm damage roof repair or free roof inspection.
If your claim is denied
A denied claim does not change our inspection standards. We do not interpret your policy or tell you what it covers, but we can take another careful look at the roof itself.
- First we assess whether any damage was overlooked and whether additional documentation is warranted.
- If overlooked damage exists, you get an updated package of photos, findings and estimates to present to your carrier.
- If the roof looks repairable, and you authorize it, we evaluate and attempt the repair, documenting what we find along the way.
- If the repair succeeds, we complete the work. If it turns out a proper repair cannot be made, we document that too and give you the findings for your carrier.
We do the same thorough evaluation whether you are paying retail or going through insurance. We cannot guarantee an approval, a replacement or any coverage decision. Our responsibility is to document the physical condition of your property and recommend the roofing work it needs.
Insurance claim questions
Should I call my insurance company or a roofer first?
Many homeowners start with a free inspection so they know whether there is real damage before filing. Check your policy for any reporting deadlines, and contact your insurer whenever you are ready.
Will you file the claim for me?
No. The claim is between you and your insurance company, so you file it and stay in charge of it. We give you the documentation package, our photos plus the estimate, to use as you decide.
What if my claim is denied?
Ask your insurer to explain the decision in writing, then let us look again. A denial does not change how we inspect: we check whether damage was overlooked and whether more documentation is warranted, and if the roof is repairable we can evaluate a repair. See the section above for how that works.
Does insurance cover an old roof?
It depends on your policy. Some policies pay replacement cost and others pay actual cash value or limit coverage for older roofs. Your agent can tell you what yours includes.
Can you start work before the claim is settled?
For an active leak, we can make temporary repairs to protect your home. Document the condition first and keep receipts, and check with your insurer about emergency repairs.